A Significant Shift in Kenya’s Property Market
The planned disposal of approximately KSh 20 billion in Kenyan real estate assets by Mauritius-based Grit Real Estate Income Group offers a significant insight into the financial pressures facing highly leveraged property businesses.
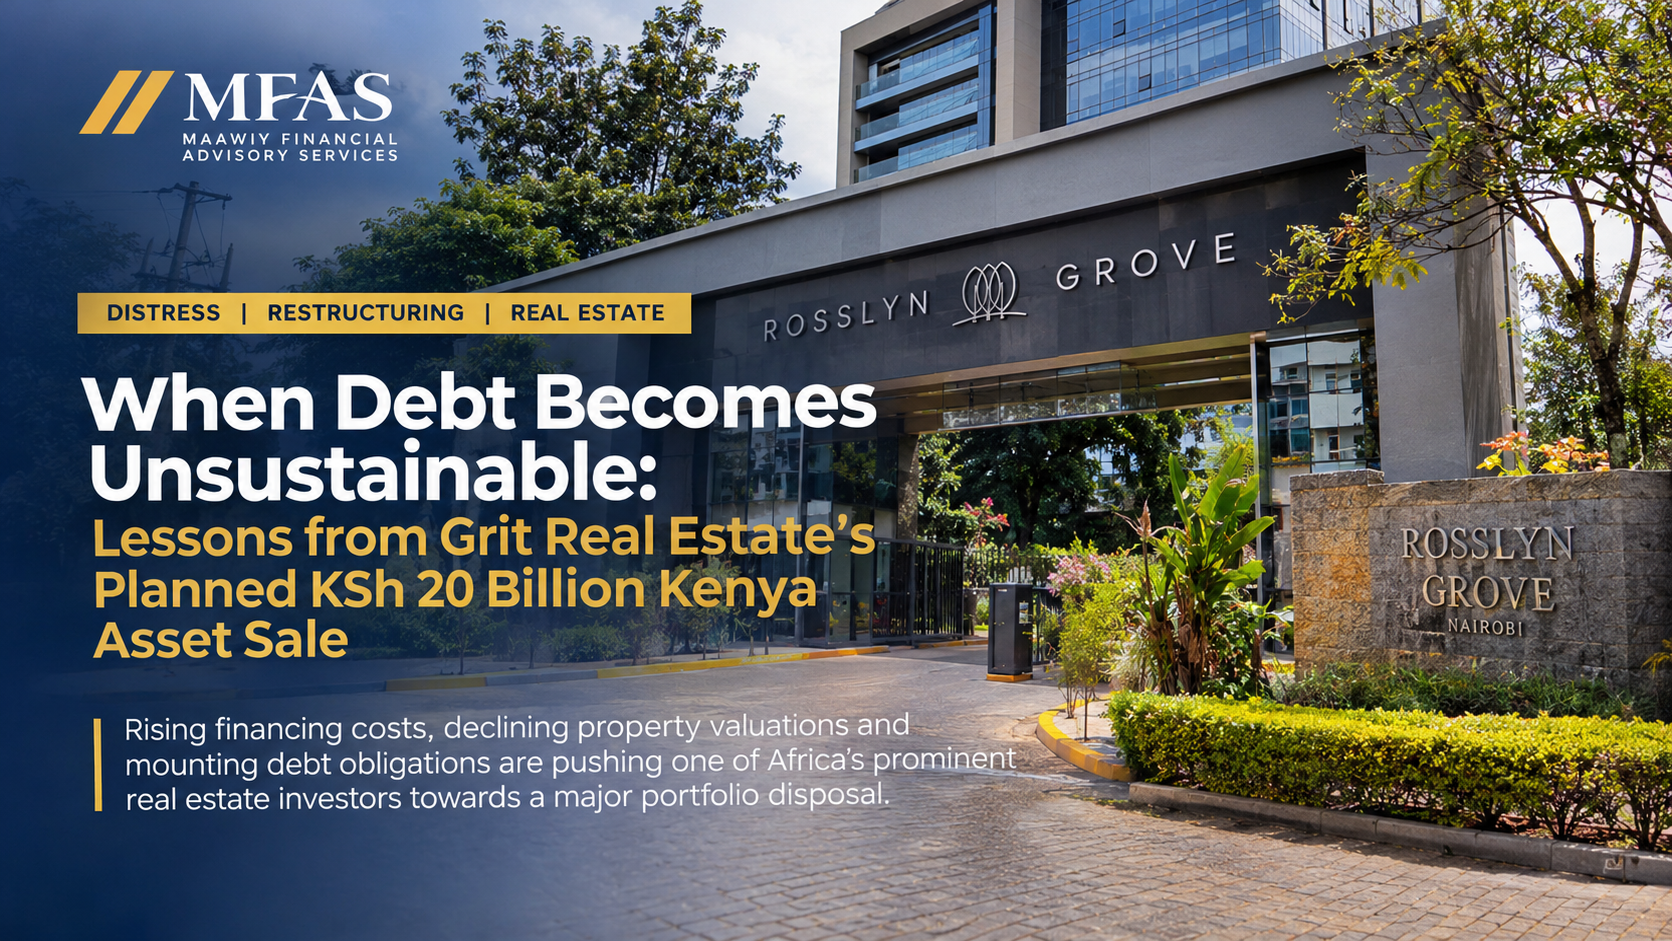
The company’s proposed exit includes prominent properties such as Rosslyn Grove in Nairobi, Buffalo Mall in Naivasha, Eneo at Tatu City, Orbit Complex in Athi River and the Imperial Distribution Centre along Mombasa Road.
According to disclosures reported by Business Daily on 4 November 2026, Grit’s decision to accelerate asset disposals follows rising financing costs and a significant decline in the value of its real estate investments.
The development is particularly notable given the profile of the assets involved. These are established commercial, residential, logistics and retail properties within Kenya’s property market.
However, the situation demonstrates an important distinction in corporate finance: owning valuable assets does not necessarily mean a business is financially sustainable.
How Financing Costs Can Reshape a Property Business
Real estate development is inherently capital-intensive. Developers frequently rely on substantial borrowing to finance land acquisition, construction, property management and expansion.
This model can be effective when rental income remains stable, borrowing costs are manageable and asset valuations continue to support the underlying debt.
The challenge emerges when these assumptions change.
Grit’s financial difficulties have been compounded by higher benchmark interest rates affecting its predominantly US dollar-denominated borrowing. As financing costs rise, the proportion of rental income available to service debt declines.
At the same time, falling property valuations can weaken the collateral supporting existing facilities.
This creates a difficult financial environment in which a company may continue to own income-generating properties but face growing liquidity and refinancing pressures.
For property businesses operating in Kenya, the broader lesson is that debt structures must remain resilient to changes in interest rates, currency movements, rental performance and market valuations.
Asset Disposal: A Strategic Response or a Sign of Distress?
Selling assets is not inherently a sign of business failure. Portfolio disposals are a common capital management strategy used by businesses to improve liquidity, reduce debt and refocus operations.
The distinction lies in the circumstances surrounding the sale.
A strategic disposal is generally undertaken when management has sufficient flexibility to select assets, negotiate favourable terms and determine the timing of the transaction.
A distress-driven disposal, however, may occur when creditors are exerting pressure, refinancing options have narrowed, or the business needs immediate liquidity to meet financial obligations.
Under such circumstances, the company may have less negotiating power and could face the risk of selling assets below their optimal market value.
Grit’s proposed portfolio exit illustrates the complexities of managing a large real estate business under financial pressure. The company has indicated that the disposal programme involves multiple transactions and remains subject to relevant agreements and approvals.
For lenders, investors and other stakeholders, the ultimate outcome will depend not only on the value of the properties but also on the structure, timing and execution of the transactions.
The Implications for Creditors and Financial Institutions
The proposed asset sales also raise important considerations for financial institutions with exposure to property developers.
Kenyan lenders, including Absa Bank Kenya and NCBA Group, are among the institutions associated with Grit’s financing arrangements.
When a borrower enters financial distress, lenders must assess several interconnected issues:
-
Collateral adequacy: Whether the current market value of secured assets remains sufficient to cover outstanding facilities.
-
Debt recovery prospects: Whether repayment through asset disposal offers a better outcome than continued enforcement or restructuring.
-
Cash flow sustainability: Whether remaining operations can generate sufficient income to meet ongoing obligations.
-
Transaction execution risk: Whether asset sales can be completed within the required timeframe and with the necessary approvals.
-
Stakeholder coordination: Whether lenders, shareholders, regulators and other parties can agree on a viable resolution.
The process highlights why effective credit risk management extends beyond the initial approval of a facility. Continuous monitoring of borrower performance, asset valuations and debt service capacity is essential.
Early Financial Restructuring Could Make the Difference
One of the most important lessons from corporate distress is the value of early intervention.
Businesses experiencing financial pressure often delay restructuring until liquidity becomes severely constrained. By that stage, available options may be limited, creditor relationships may have deteriorated, and the cost of resolving the situation may have increased significantly.
A proactive restructuring process can provide a company with greater flexibility.
Depending on the circumstances, potential interventions may include:
-
Renegotiating loan repayment schedules and covenant requirements.
-
Refinancing existing facilities to improve debt maturity profiles.
-
Reviewing operating costs and non-core investments.
-
Disposing of selected assets to reduce debt exposure.
-
Restructuring capital arrangements with lenders and investors.
-
Developing a comprehensive turnaround plan supported by realistic financial forecasts.
The objective is not simply to reduce debt. It is to establish a financially sustainable operating model capable of meeting obligations while preserving enterprise value.
In certain cases, a well-managed restructuring can protect business operations, support creditor recoveries and reduce the likelihood of formal insolvency proceedings.
What Kenyan Businesses Should Take Away
Grit’s planned asset disposal provides a timely reminder that financial distress can affect businesses across sectors, including companies with substantial assets and established market positions.
For Kenyan businesses, particularly those operating in real estate, construction, hospitality, manufacturing and other capital-intensive industries, sustainable financing structures are critical.
Management teams should regularly evaluate whether their borrowing remains aligned with their operating cash flows, whether their debt obligations can withstand adverse market conditions, and whether early corrective action is required.
For creditors, the situation reinforces the importance of identifying emerging financial distress before it becomes a recovery challenge.
For investors, it underscores the need to look beyond asset ownership and headline valuations when assessing the financial health of a company.
Ultimately, the ability to recognise financial pressure early and implement appropriate restructuring measures can be the difference between a controlled turnaround and a forced asset disposal.
MFAS Perspective
At MFAS, we recognise that financial distress is rarely the result of a single event. It often develops through a combination of financing decisions, operational pressures, market changes and delayed intervention.
Our focus is on helping businesses and stakeholders navigate financial complexity through structured financial advisory, restructuring, insolvency-related support and strategic assessment.
The Grit Real Estate case reinforces a fundamental principle of financial management: the value of a business is not determined solely by the assets it owns but also by its ability to sustain its obligations and preserve value over time.
When financial pressure begins to emerge, early assessment and informed intervention can create opportunities that may no longer be available once distress deepens.
Facing financial pressure or considering a restructuring?
Engage MFAS for professional financial advisory and restructuring support